Enter nationality, salary, and pay period then click Calculate to see a full breakdown — net salary, SPF deductions, employer cost, and annual equivalents.
How to Use the Oman Payroll Calculator 2025
Calculate net salary, Social Protection Fund contributions, total employer cost, and optional VAT in one click. Covers Omani nationals and expatriates under current Oman payroll regulations.
Select nationality and pay period
Choose Omani National or Expatriate. Nationality determines whether Social Protection Fund contributions apply — Omani nationals are subject to 8% employee deductions and 12.5% employer contributions. Expatriates are generally exempt from SPF in the same format. Select Monthly or Annual as your input period; the calculator displays results in both automatically.
Enter gross salary and optional VAT
Enter the gross salary in Omani Rials (OMR). Personal income tax is 0% in 2025, so no income tax deduction applies. Optionally, enter a VAT base amount to calculate the 5% VAT on a business invoice or purchase alongside the payroll figures — this does not affect the salary calculation and appears as a separate section below the payroll breakdown.
Read and download the results
Results show gross salary, SPF employee deduction (if applicable), net take-home pay, employer SPF contribution, and total employer cost — with monthly and annual figures. Click Download Breakdown to export a CSV file for payroll records or HR reporting. All figures use three decimal places in OMR format.
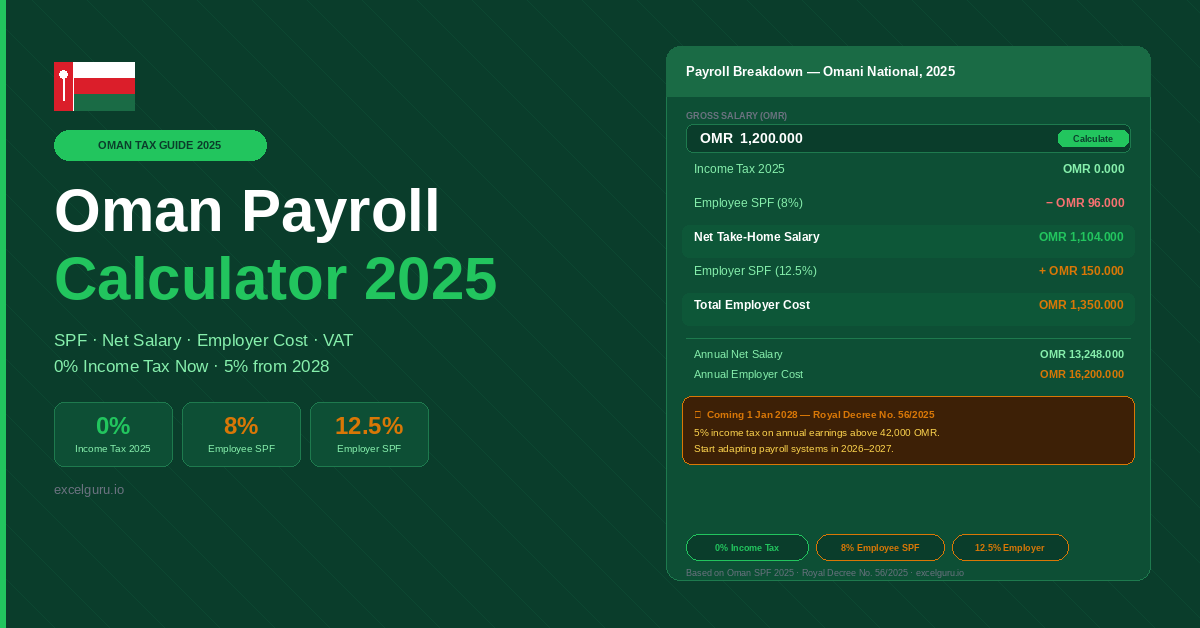
For an Omani national on 1,200 OMR gross, the employee takes home 1,104 OMR while the employer pays 1,350 OMR total. That 150 OMR gap — the 12.5% employer SPF contribution — is the true labour cost above the stated salary. When planning headcount or comparing Omani national vs expatriate hiring costs, always use the total employer cost figure rather than the gross salary.
Oman Tax and Payroll Guide 2025 — Complete Reference
Oman's personal income tax position, Social Protection Fund structure, VAT obligations, and the 2028 income tax changes — everything needed for payroll compliance and financial planning in Oman.
Personal income tax in Oman — 0% in 2025
As of 2025, Oman does not impose personal income tax on employment income. The rate on salaries is 0% for both Omani nationals and expatriates. There are no progressive tax brackets, no income threshold, and no payroll withholding mechanism. Employee take-home pay is the gross salary minus only the Social Protection Fund deduction — where applicable. Any Oman salary calculator for 2025 should show zero income tax deduction, reflecting the current statutory position.
Oman remains one of the most competitive personal tax environments in the GCC for employment income. However, this position is scheduled to change significantly in 2028 under Royal Decree No. 56/2025. Payroll systems should be built with flexibility to add income tax withholding before that date — organisations that wait until 2027 will face a compressed implementation timeline.
Social Protection Fund contributions — 2025 rates
Although personal income tax is zero, Social Protection Fund (SPF) contributions represent the primary payroll cost component beyond gross salary for Omani nationals. The SPF covers Social Security, Job Security Fund, and Occupational Injury insurance. Contributions are calculated as a percentage of gross salary and split between employee and employer.
| Contribution Type | Employee (Omani) | Employer (Omani) | Expatriate |
|---|---|---|---|
| Social Security | 7% | 10.5% | Exempt |
| Job Security Fund | 1% | 1% | Exempt |
| Occupational Injury | — | 1% | — |
| Total | 8% | 12.5% | 0% |
For Omani nationals, the 8% employee deduction reduces take-home pay to 92% of gross salary. Simultaneously, the employer contributes a further 12.5% on top of the gross salary. Together, the total employer cost is gross salary multiplied by 1.125. This 20.5% total wedge between net pay and employer cost is essential for accurate workforce budgeting and compensation planning.
Expatriate employees — payroll obligations
Expatriate employees are generally exempt from the Social Protection Fund contribution structure that applies to Omani nationals. No Social Security or Job Security Fund deductions apply to their salary under the standard format. They are also subject to 0% personal income tax in 2025. Employer obligations for expatriates depend on specific contract terms and any applicable statutory requirements under the employment visa category. However, expatriate salaries do not attract SPF employer contributions in the standard structure, making expatriate labour costs more straightforward to calculate than Omani national payroll.
VAT in Oman — 5% since 2021
Oman introduced a 5% Value Added Tax in April 2021. VAT applies to most goods and services and operates under a standard output VAT minus input VAT recovery mechanism. Employment income is completely outside the VAT system — it is a separate obligation for businesses issuing taxable invoices. Businesses exceeding the registration threshold must register with the Tax Authority of Oman and file periodic VAT returns. The optional VAT section in this calculator lets businesses calculate the VAT amount on a specific transaction alongside their payroll figures for convenience.
Under Royal Decree No. 56/2025, Oman will introduce personal income tax at 5% on annual earnings exceeding 42,000 OMR. Payroll withholding becomes mandatory from that date. Employer reporting requirements will expand significantly. Organisations should begin adapting payroll infrastructure in 2026–2027 to ensure compliance readiness well before the deadline.
Oman payroll and tax timeline
Frequently Asked Questions — Oman Tax and Payroll 2025
Common questions about SPF contributions, expatriate obligations, VAT, and the 2028 income tax changes in Oman.