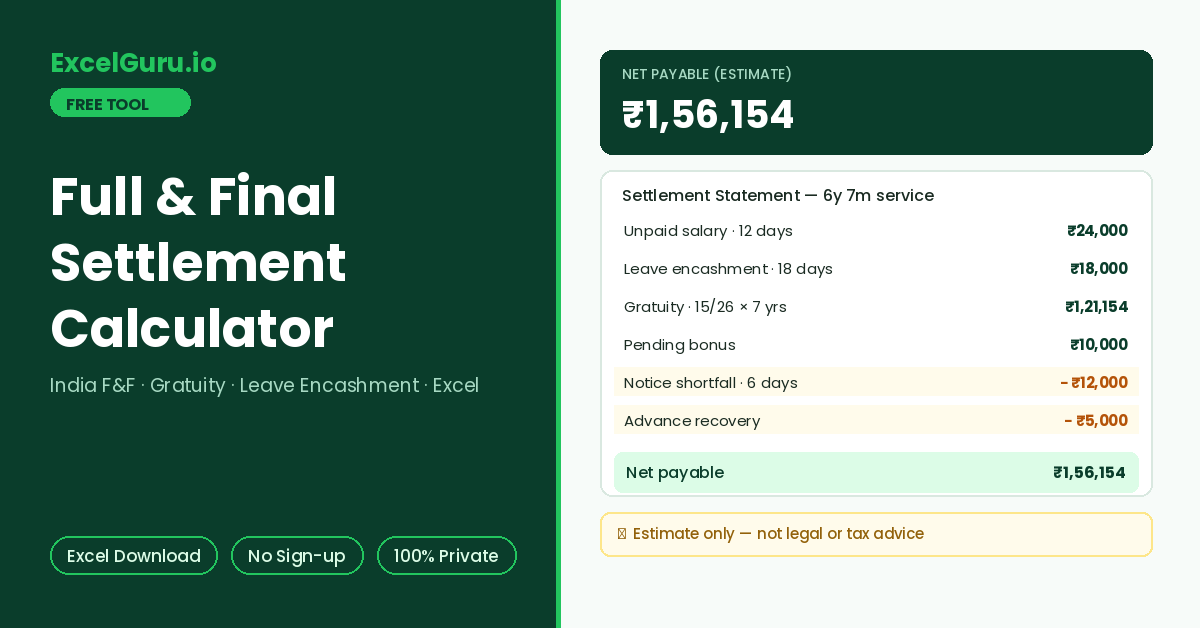
The itemized F&F statement with gratuity eligibility and net payable appears here.
How to Use the Full and Final Settlement Calculator
Estimate an Indian F&F settlement from the standard components. These cover unpaid final-month salary, leave encashment, gratuity with the eligibility check, pending bonuses, and recoveries such as notice shortfall. The itemized statement downloads as an Excel file.
Enter salary and service length
Type monthly gross and monthly basic plus DA — gratuity and most leave encashment use basic, while unpaid salary uses gross. Add completed years and extra months of service for the gratuity eligibility check.
Add balances and recoveries
Fill unpaid salary days, the leave balance to encash with its basis, and any pending bonus. Then add deductions: notice shortfall days and outstanding advances or loans.
Review the statement and export
The result itemizes each payment and deduction, shows the gratuity computation with rounding, and totals to net payable. Download the Excel statement to cross-check against the employer’s F&F sheet.
Gratuity rounds service to the nearest full year: 6 years 7 months counts as 7 years, while 6 years 5 months counts as 6. That single month around the half-year mark changes the payout by one full year’s slab of 15 days of basic pay. Therefore, exit-date timing near the boundary is worth checking.
F&F Components, Gratuity Formula, and Worked Example
Everything inside an Indian F&F: the gratuity formula with its eligibility rule, leave encashment conventions, common deductions, and Excel formulas to verify a statement.
The components of an F&F statement
A full and final settlement nets payments against recoveries. Payments typically include unpaid salary for days worked in the final month, encashment of unused earned leave, gratuity where service qualifies, and pending bonus, incentives, or reimbursements. Recoveries run the other way. These include notice shortfall for unserved days, outstanding salary advances or loans, and occasionally asset or training-bond recoveries per contract.
Gratuity — the eligibility rule and the 15/26 logic
Under the Payment of Gratuity Act framework, gratuity generally becomes payable after around five years of continuous service. The amount is 15 days of last-drawn basic plus DA per completed year. Meanwhile, the 15/26 fraction exists because the convention treats a month as 26 working days — so 15⁄26 of a month’s basic per year of service. Service beyond six months in the final year rounds up to a full year. A statutory ceiling on total gratuity also applies and gets revised by notification, so large payouts should be checked against the current limit.
Leave encashment conventions
The basis changes the money meaningfully: 18 days on a 30,000 basic yields 18,000 under ÷30 but 20,769 under ÷26. Consequently, the calculator makes the basis an explicit dropdown rather than a hidden assumption, and the exported statement records which one was used.
Worked example — 6 years 7 months, ₹60,000 gross
Basic+DA is 30,000. The employee works 12 days of the final month: 60,000 ÷ 30 × 12 = 24,000 unpaid salary. Leave balance of 18 days on the ÷30 basic basis adds 18,000. Service rounds to 7 years, so gratuity is 30,000 × 15⁄26 × 7 = 121,154. With a 10,000 pending bonus, payments total 173,154. Against a 6-day notice shortfall recovery of 12,000 and a 5,000 advance, net payable is 156,154.
Unpaid salary is =Gross/30*DaysWorked. Leave encashment is =Basic/30*LeaveDays (swap the divisor per policy). Gratuity rounding uses =Years+IF(Months>=6,1,0), then =Basic*15/26*RoundedYears. Finally, net payable is =SUM(payments)-SUM(recoveries). The downloaded statement lays these out line by line with your figures.
Timelines and what to check before signing off
Notably, the wage code framework directs employers to settle dues within two days of exit in covered cases. Many companies still operate a 30–45 day F&F cycle in practice. Before accepting a statement, check four things. Verify the day-count basis on unpaid salary, the leave balance against your own records, the gratuity rounding, and every recovery line against signed documents. Discrepancies concentrate in exactly these four places.
Gratuity eligibility details, the statutory ceiling, TDS on each component, and state-specific rules change by notification and case law. Some components are tax-exempt within limits and taxable beyond them, which this calculator does not model. Treat the output as a verification aid and consult HR, a CA, or a lawyer for a binding position on any disputed amount.
Frequently Asked Questions
Common questions about F&F settlements, gratuity, deductions, and the Excel statement.